Cash-Flowing Investment Properties in Franklin County FL for 2026
September 15, 2026 by Melissa Chandler
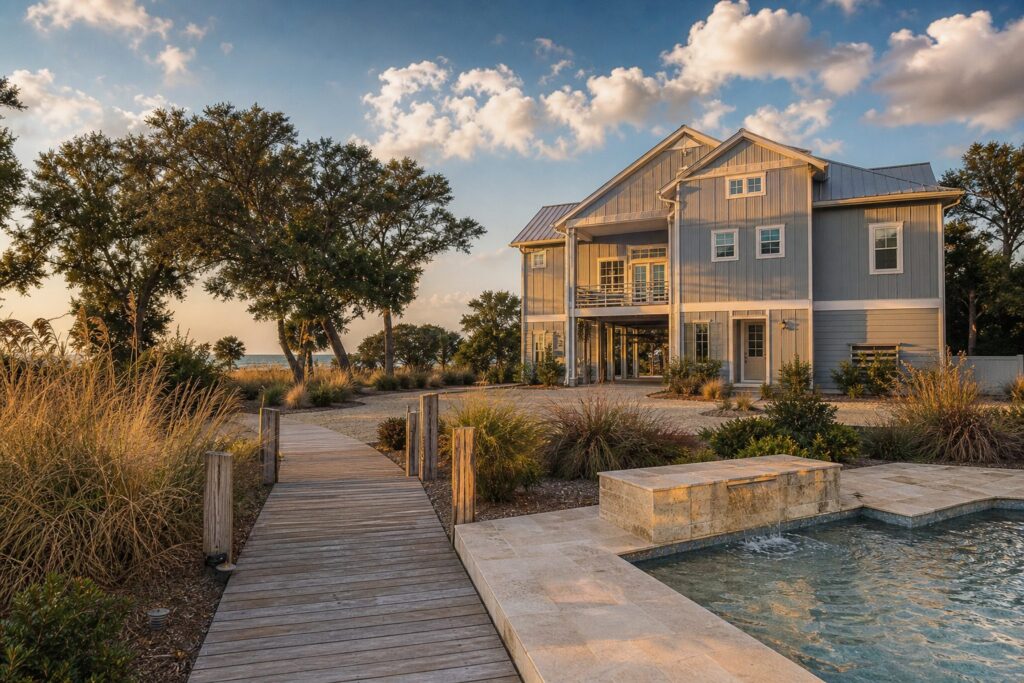
What types of investment properties in Franklin County FL are actually cash-flowing in 2026, and which areas should I avoid?
Vacation rentals on St. George Island and workforce housing in Eastpoint or Carrabelle offer the best cash-flow potential, while overpriced Plantation-side beachfront and aging Lanark Village stock carry the most risk.
Why This Matters Right Now in Franklin County
I grew up in this county. My family moved to St. George Island in 1968, and my father was a realtor on this coast before I ever understood what a closing was. So when I tell you the investment landscape in Franklin County is shifting, it comes from watching this market through decades of change, not just a spreadsheet.
Franklin County’s median sale price has climbed over 8% year over year, pushing past $254,000 through August 2026. Meanwhile, inventory has tightened to just 59 available homes, down from 72 a year ago. Sales volume is actually down, with 211 homes sold through August compared to 227 in 2025. That means fewer deals are happening, but prices keep climbing. For investors, this combination demands sharper underwriting than ever.
The typical home value across the county sits around $425,681, but that number gets pulled upward by high-end St. George Island homes for sale. The gap between that figure and the actual median sale price tells you everything: this is a bifurcated market, and where you buy within Franklin County matters more than whether you buy.
Which Franklin County Properties Are Actually Producing Cash Flow in 2026
Short-Term Vacation Rentals on St. George Island
St. George Island remains the engine of Franklin County’s investment economy. Gulf-side homes with three or more bedrooms, updated kitchens, and private pools are consistently booking at premium nightly rates during peak season. What I tell investors is simple: underwrite for 55 to 65% annual occupancy, not the 80% that sounds nice on a projection sheet. The shoulder months from October through February will test your numbers.
One investor I worked with recently purchased a four-bedroom Gulf-view home on St. George Island, ran conservative occupancy numbers, and still projects positive cash flow after insurance, property management, and maintenance reserves. The key was buying below $500,000 and not overpaying for direct beachfront where insurance costs can eat your margins alive.
St. George Island houses in the mid-island section often offer the best balance of rental demand and manageable acquisition cost. You get the beach proximity guests want without the extreme insurance premiums of front-row Gulf properties.
Workforce Rentals in Eastpoint and Carrabelle
Here is where most investors overlook the opportunity. Franklin County’s top employment sectors, including public administration, retail trade, and professional services, employ roughly 4,680 people who need affordable places to live. With a population of only about 13,100 and zero multifamily permits pulled in 2025 (all 112 permits were single-family), there is a genuine shortage of rental housing for working residents.
Eastpoint and Carrabelle offer entry points below the county median. A modest two- or three-bedroom home in Carrabelle, purchased at or below $200,000, can produce steady monthly income from workforce tenants without the seasonal volatility of vacation rentals. The mean commute time in Franklin County is just 19.3 minutes, so these locations are convenient for workers commuting to Apalachicola or government offices.
Small Multifamily and Duplex Conversions
Since Franklin County saw zero multifamily building permits in 2025, there is a clear supply gap. If you can acquire and convert a property into a two- to four-unit configuration, you are positioning yourself where almost no competition exists. Having closed over 300 transactions in this market over 13 years, I can tell you that these opportunities do not show up on listing portals. They require local relationships and knowing which properties have the zoning flexibility to support a conversion.
The Real Cost of Owning Investment Property in Franklin County FL
Before you run your cash-flow projections, you need honest numbers on carrying costs. This is where I see out-of-area investors get burned most often.
- Insurance: Citizens, Florida’s insurer of last resort, covers 115 homes in Franklin County at an average premium of about $2,575 per year. Private market quotes for coastal or flood-zone properties can run significantly higher. This is not optional.
- Financing: At today’s 6.52% 30-year rate, and with investment property loans typically running 0.5 to 0.75% higher, your monthly principal and interest on the typical home runs near $2,372 before property tax.
- Price-to-Income Ratio: The typical home costs about 6.79 times the local median household income of $64,105, which is roughly 38% above the Florida norm. That stretched ratio means appreciation alone cannot bail out a bad deal.
- Property Management: Few professional management companies serve this rural market. If you are buying a vacation rental on St. George Island and do not live locally, budget 25 to 30% of gross rental income for management, cleaning coordination, and maintenance.
What does all this actually mean for your wallet? It means a St. George Island home for sale at $450,000 with a 25% down payment, investment-rate financing, insurance, taxes, and management could need $45,000 to $55,000 in gross annual rental income just to break even. That is achievable on the right property, but it demands discipline in your acquisition price.
Which Franklin County Areas and Property Types You Should Avoid
Overpriced Beachfront on St. George Island’s Plantation Side
The Plantation is the gated community on the west end of the island. Properties there routinely list between $800,000 and $1.5 million. With the county appearing roughly 38% overvalued relative to local income fundamentals, the premium end of the market carries the most downside risk. Insurance and maintenance on beachfront Plantation homes are extreme due to hurricane exposure, salt-air corrosion, and mandatory flood zone requirements. About 18% of Franklin County listings have already cut their price, and higher-priced properties tend to sit longest.
One couple I advised last year was drawn to a stunning Plantation-side property. After we ran the real numbers, including a $6,000-plus annual insurance estimate and the seasonal vacancy during winter months, the projected cash flow was negative by over $1,200 per month. They redirected to a mid-island property and are now cash-flow positive.
Lanark Village
Lanark Village, established from old military officer’s quarters after the base closed, has an aging housing stock with limited appreciation potential. The retiree-heavy demographic limits rental demand, and the properties themselves often require significant capital expenditure to bring up to rentable condition. Unless you find a deeply discounted deal with a specific exit strategy, this is a neighborhood better suited for owner-occupants than investors seeking returns.
Speculative Vacant Land
With only 211 sales through August in the entire county and a Momentum Market Score of just 21 out of 100 (indicating a frothy, overextended market), tying up capital in vacant land hoping for future appreciation is a risky play. Liquidity is thin here. If you need to exit quickly, you may not be able to.
How to Underwrite a Franklin County Investment Property the Right Way
You need a framework that accounts for the realities of this specific market. Here is what I walk my clients through:
- Start with conservative occupancy. For vacation rentals on St. George Island, model 55 to 65% annually. For long-term rentals in Eastpoint or Carrabelle, assume one month of vacancy per year.
- Use real insurance quotes, not estimates. Get actual quotes from Citizens and at least two private insurers before making an offer. The difference between a $2,500 and a $5,500 annual premium can flip a deal from positive to negative.
- Factor in the full carrying cost. Principal, interest, insurance, property tax, management fees, maintenance reserves (budget 1 to 2% of property value annually for coastal properties), and cleaning/turnover costs for short-term rentals.
- Know your exit. With only 59 homes on the market and roughly 211 annual sales, Franklin County is not a market where you can flip quickly if things go sideways. Buy with a five-year minimum hold in mind.
With 33 five-star reviews from clients and recognition as a top 6% agent among Berkshire Hathaway HomeServices agents nationwide, I have seen what separates successful Franklin County investors from those who lose money. It almost always comes down to underwriting honestly and knowing the local carrying costs for Florida Gulf Coast real estate before you write an offer.
Frequently Asked Questions
Can I cash flow on a St. George Island vacation rental in 2026?
Yes, but only if you buy at the right price point and underwrite conservatively. Mid-island homes with three to four bedrooms, pools, and updated interiors in the $400,000 to $550,000 range offer the most realistic path to positive cash flow after accounting for insurance, management, and seasonal vacancy. Assume 55 to 65% annual occupancy, not peak-season projections.
What is the median home price in Franklin County FL right now?
The median sale price through August 2026 is over $254,000, up more than 8% from the prior year. Average sale prices have risen from $256,000 in 2025 to over $284,000 in 2026. Keep in mind that the typical home value index runs around $425,681 due to high-end St. George Island real estate pulling the average upward.
Are long-term rentals viable in Franklin County?
They can be, particularly in Eastpoint and Carrabelle where entry prices are lower. The local workforce in public administration, retail, and professional services needs affordable housing. With zero multifamily permits issued in 2025, rental supply is constrained, which supports stable occupancy for modestly priced long-term units.
How much is homeowners insurance for investment properties in Franklin County FL?
Citizens, the state-backed insurer, averages about $2,575 per year for the 115 homes it covers in Franklin County. Private market quotes for coastal, flood-zone, or older-roof properties can be significantly higher. Always obtain actual quotes before finalizing your investment analysis.
Should I avoid Lanark Village as an investor?
Generally, yes. Lanark Village has older, smaller housing stock originally built as military officer’s quarters. The area’s retiree-heavy demographic limits rental demand, and the properties often need substantial renovation. Unless you find a deeply discounted deal with a clear value-add strategy, other Franklin County areas offer better returns.
What financing rates should I expect for investment properties in 2026?
Current 30-year rates sit around 6.52% for primary residences. Investment property loans typically carry an additional 0.5 to 0.75% premium. Many Franklin County transactions close as cash deals due to the vacation and second-home nature of the market. For borrowers interested in government-backed options, FHA and VA loans are available through HUD.
How tight is Franklin County housing inventory right now?
Very tight. As of the end of August 2026, only 59 homes were available, down from 72 a year prior. With 229 pending sales in the pipeline, competition for well-priced properties is real. This low inventory supports prices but also limits your acquisition options.
Is Franklin County FL overvalued in 2026?
By income-based metrics, the market appears roughly 38% overvalued, with a price-to-income ratio of 6.79 times the local median household income of $64,105. The Momentum Market Score reads 21 out of 100, signaling stretched valuations. That does not mean prices will crash, but it does mean you should not rely on appreciation to make your numbers work.
What about building new construction for rental income in Franklin County?
Builders pulled 112 permits in 2025, all single-family. At 9.0 permits per 1,000 residents, that is above the state average. New construction can work if your build cost stays competitive, but rising insurance and material costs on the coast make it essential to lock in contractor bids early and plan for wind-mitigation features that reduce long-term premiums.
How many homes sell per year in Franklin County FL?
Through August 2026, 211 homes sold, compared to 227 over the same period in 2025. This is a thin market by any standard. Low transaction volume means slower exits if you need to sell. It also means less comparable-sale data, which can make appraisals and valuations less predictable.
The Bottom Line
Franklin County is not a market where every property cash flows. The ones that do require you to be honest about insurance costs, seasonal vacancy, and management overhead. Your best bets in 2026 are well-priced vacation rentals in the mid-island section of St. George Island and affordable workforce housing in investment markets in Eastpoint or Carrabelle. Avoid overpriced Plantation-side beachfront, speculative land plays, and aging stock in Lanark Village unless you have a very specific strategy and deep pockets for renovation.
I have been around this coast my entire life, and I have helped investors navigate these decisions through over 300 transactions across 13 years. If you are seriously evaluating Franklin County real estate, I would rather have an honest conversation about what will and will not work than watch you buy the wrong property. Reach out to me, Melissa Chandler, at 850-653-7893 or visit my office at 140 W 1st Street on St. George Island. Let’s look at the real numbers together before you make a move.